From stigma to empowerment — the evolution of loans through FinPy
A user-centred overhaul anchored in field research, cultural sensitivity and structured assumption-testing — reframing credit from shame to dignity.
A user-centred overhaul anchored in field research, cultural sensitivity and structured assumption-testing — reframing credit from shame to dignity.
From Stigma to Empowerment
It is not my intention to simply pretend that a UI change increased adoption by a significant percentage, but to discuss in detail the three big problems identified through real-time CX, and how personal criticisms of the business model led to asking the right questions.
"I had only one intention in mind when I joined FinPy — to reach to the needful and whisper in their ears: 'not all debt is bad debt.'"
Research Goals & Methodology
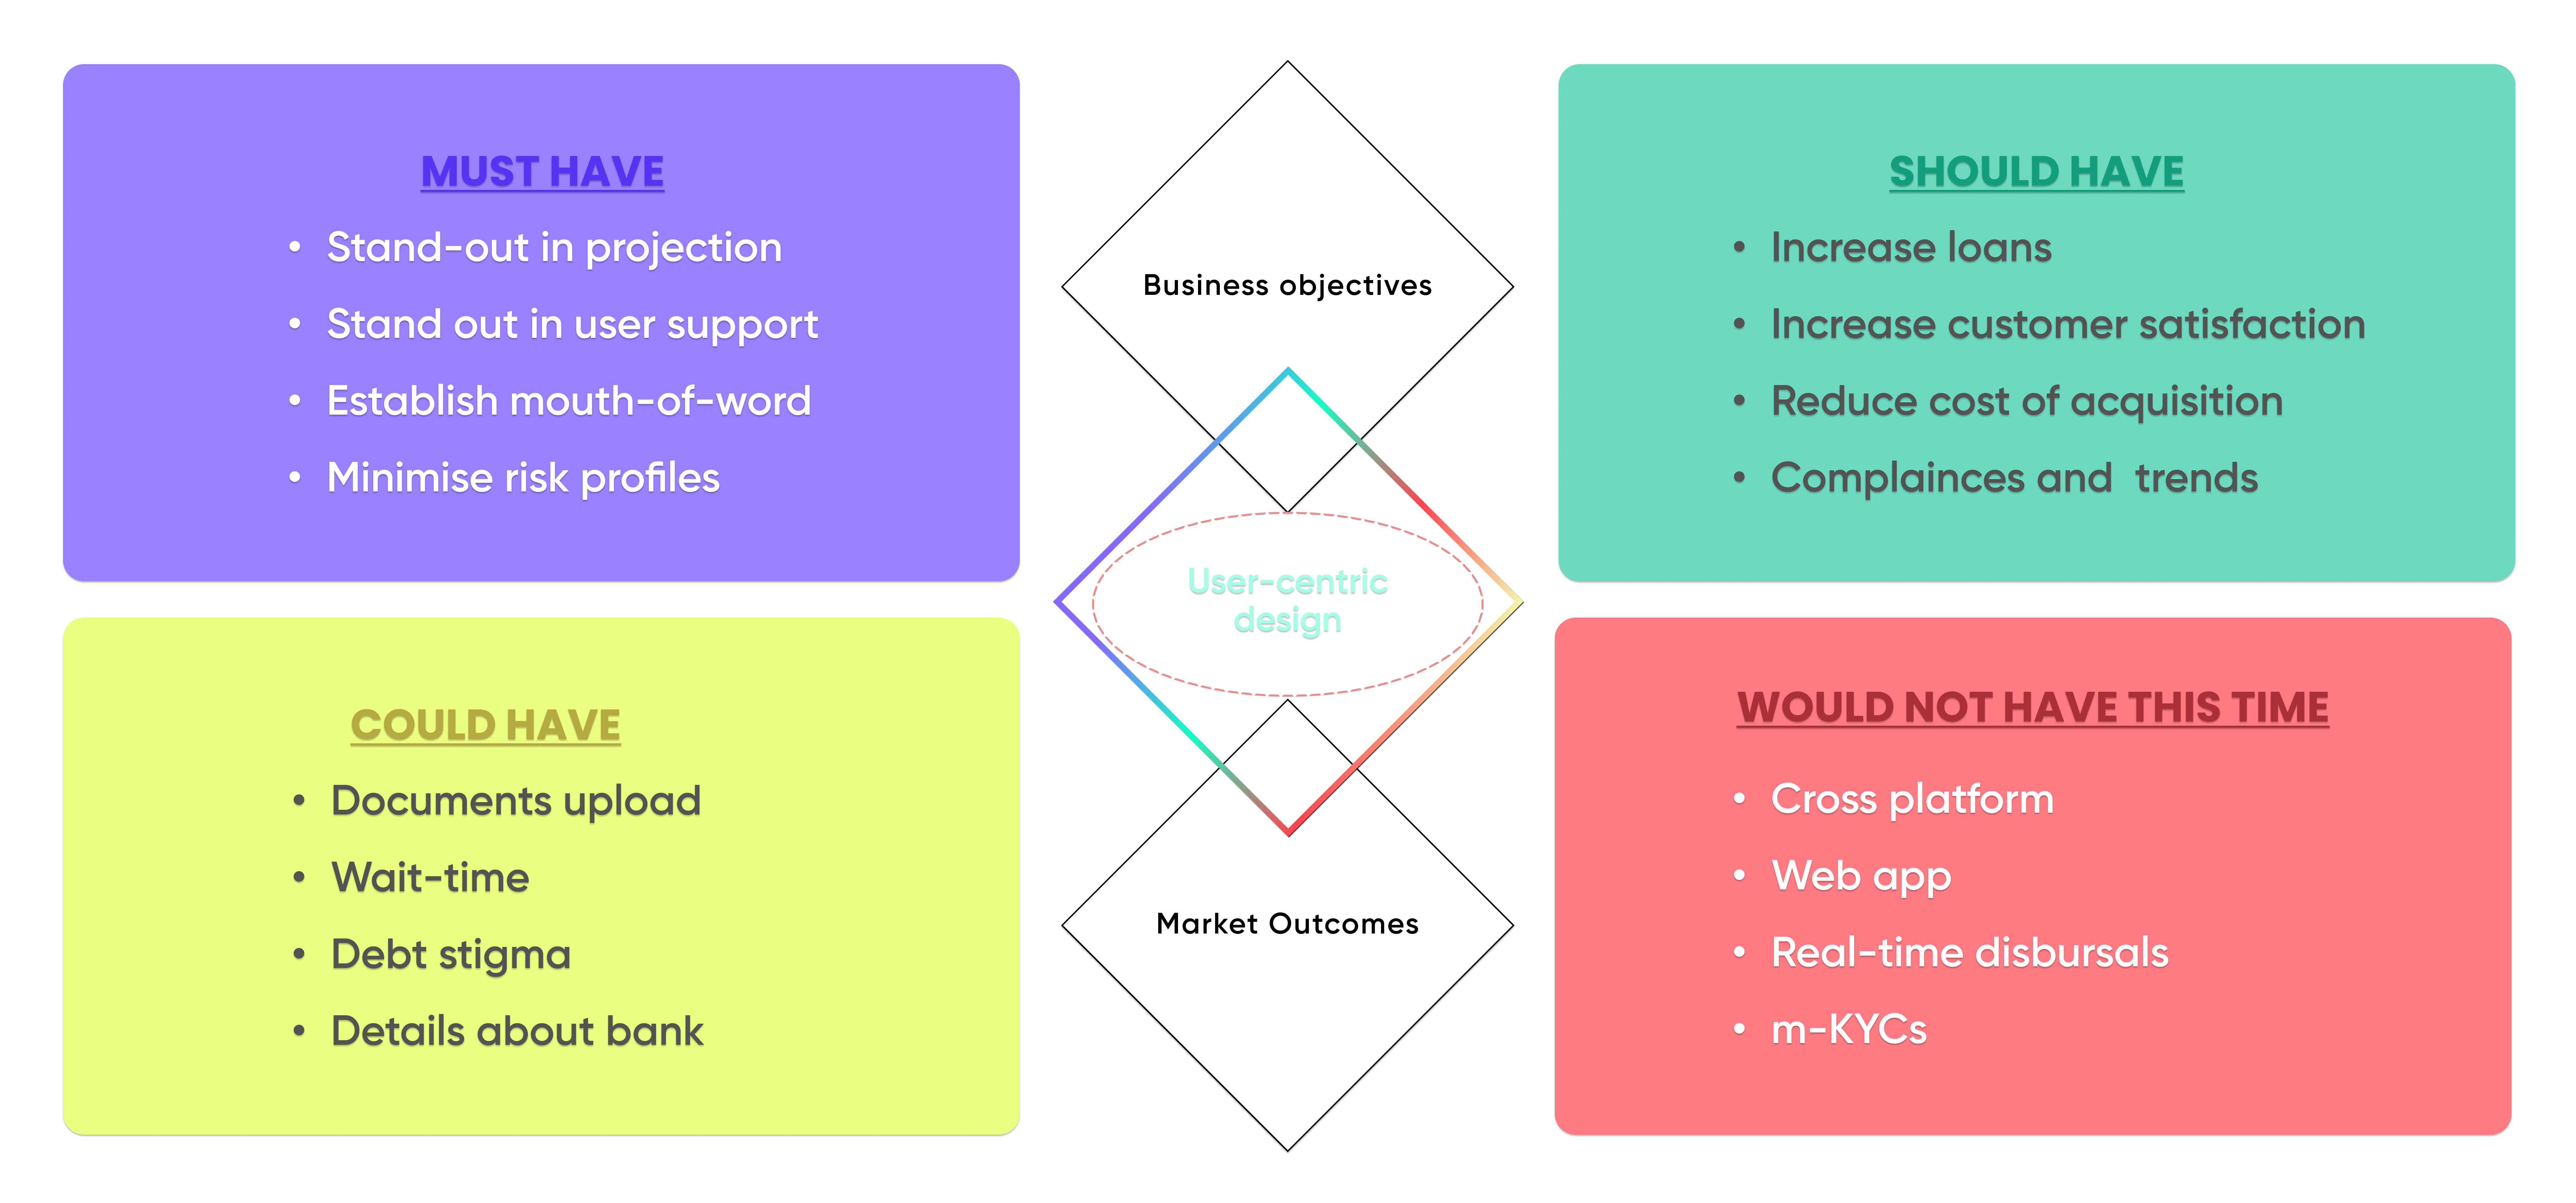
We initiated the MVP to get into the market, involving users at every major research stage. Research goals: understand target audience demographics, explore user needs and pain points with traditional loans, determine key features and user flows, and validate initial design concepts through user feedback.
Methodology: offline surveys, in-depth interviews, competitive analysis of existing personal loan apps, and prototype usability testing.
Key Findings & Audience
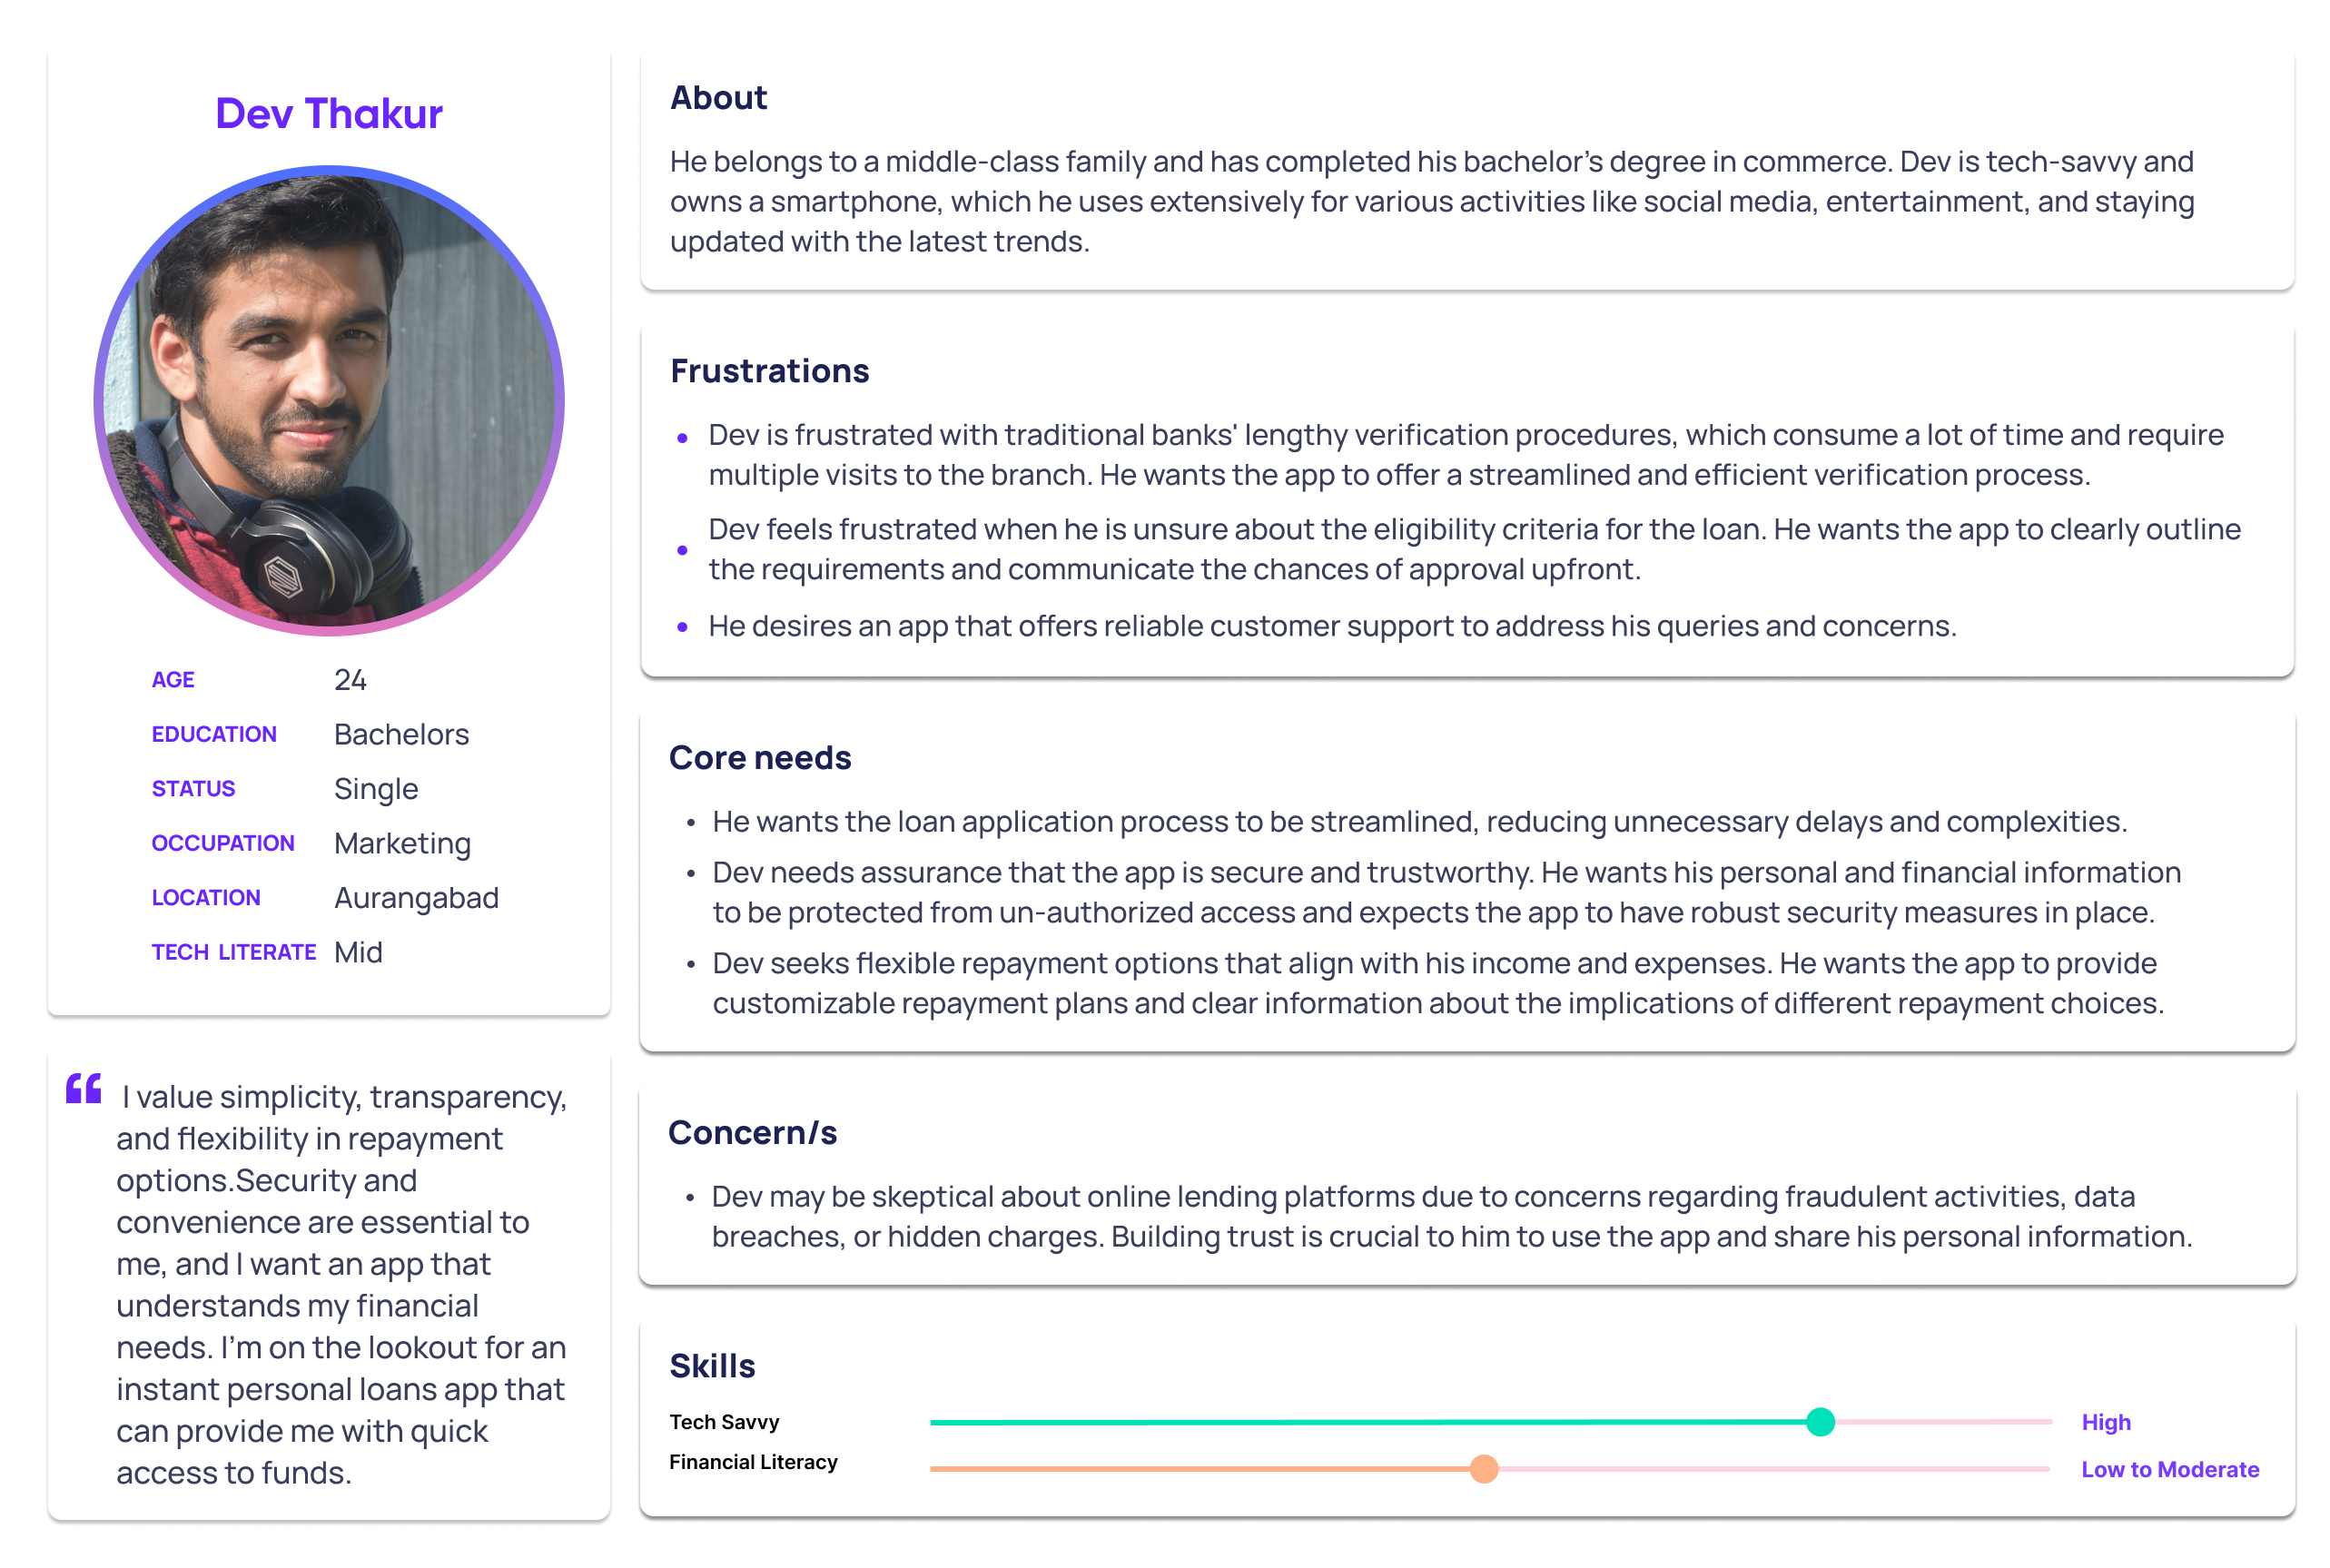
Target audience: primarily young professionals aged 25–40 with varying incomes who value convenience, speed, and flexibility. Many have limited credit histories or low credit scores, making traditional bank loans difficult to access.
Core pain points: traditional banks are time-consuming and bureaucratic. Transparency in loan terms, interest rates, and fees is crucial for building trust. Users prefer simple, intuitive applications that minimise paperwork.
Interviews & Benchmarking
We conducted online interviews using screen sharing and offline face-to-face interviews to observe non-verbal cues and build rapport. Bias was addressed by asking situational questions — 'Tell us about a time when you faced challenges paying bills on time' — instead of leading yes/no questions.
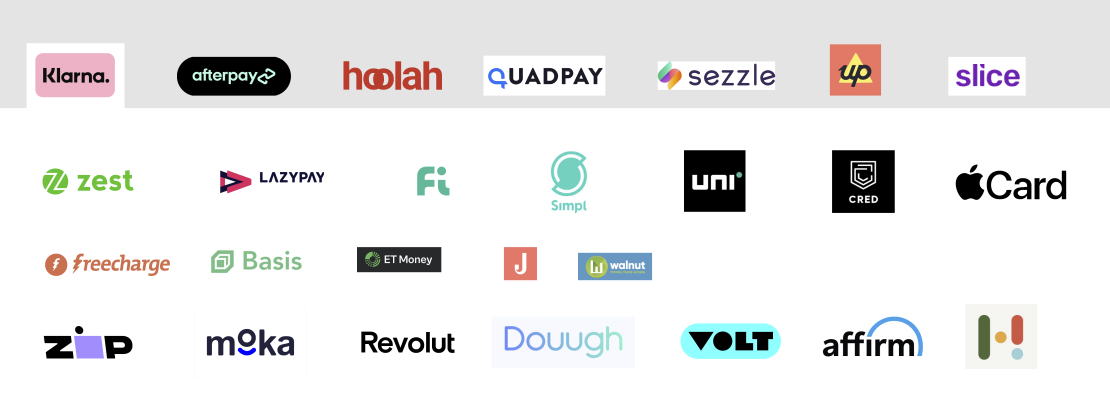
Benchmarking a Saturated Market
The personal loan app market was highly saturated, making a unique value proposition difficult to find. By placing strong emphasis on personalization, transparency, and speed, we aimed to create a compelling and differentiated offering that traditional players had ignored.
Transparent User Flows
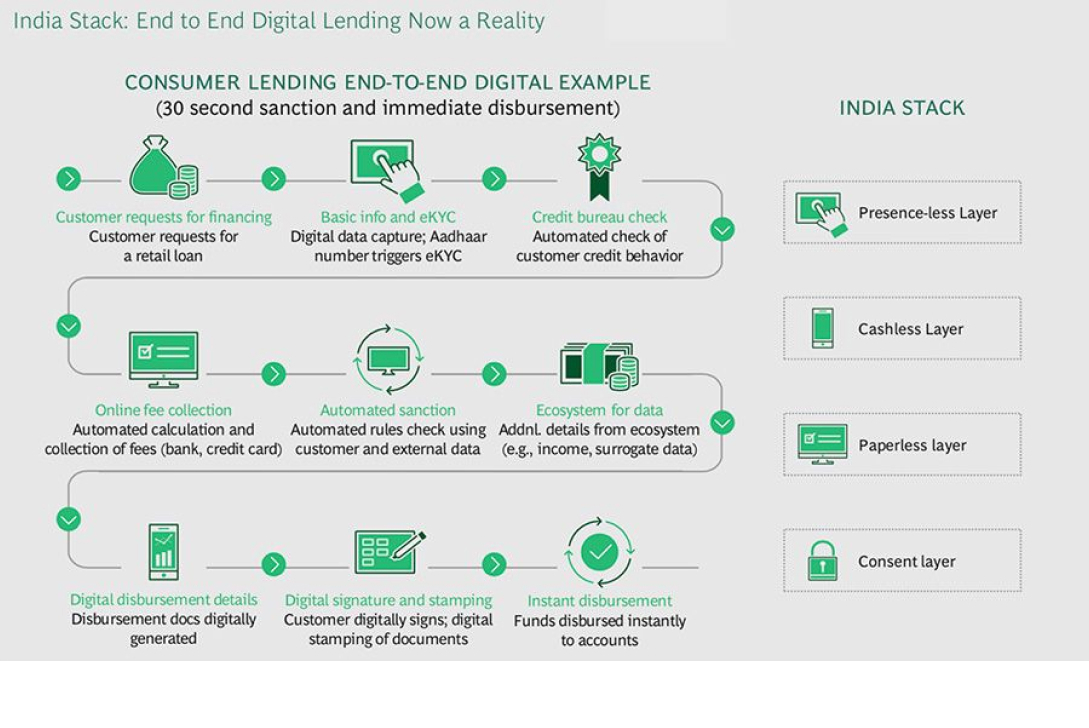
We focused on user flows that embody simplicity, personalization, and transparency. Leveraging user data, the journey was personalised — tailoring credit limits and loan terms to each user's unique financial profile. Transparency was central: interest rates, fees, and repayment schedules were communicated clearly upfront, empowering informed decisions.
Problem 1: Unrealistic Loan Tenures
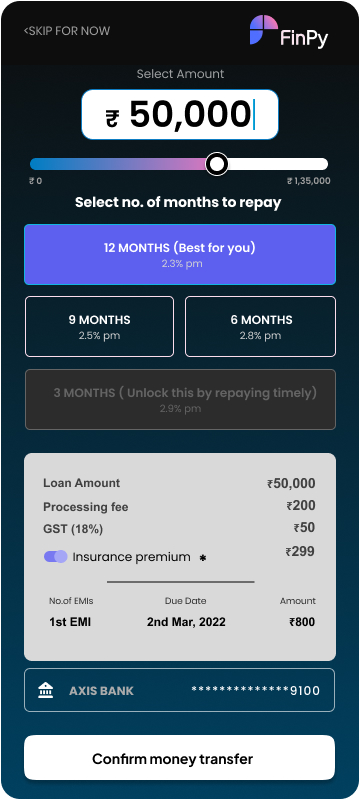
Post-launch data showed a pattern: users with very low income were choosing the minimum loan tenure — leading to defaults. The solution hypothesis: do not say tenures are unavailable, but show they are 'locked' and can be unlocked by completing specific steps. White-hat gamification without stigma.
Problem 2: Missing Salary Bank Details
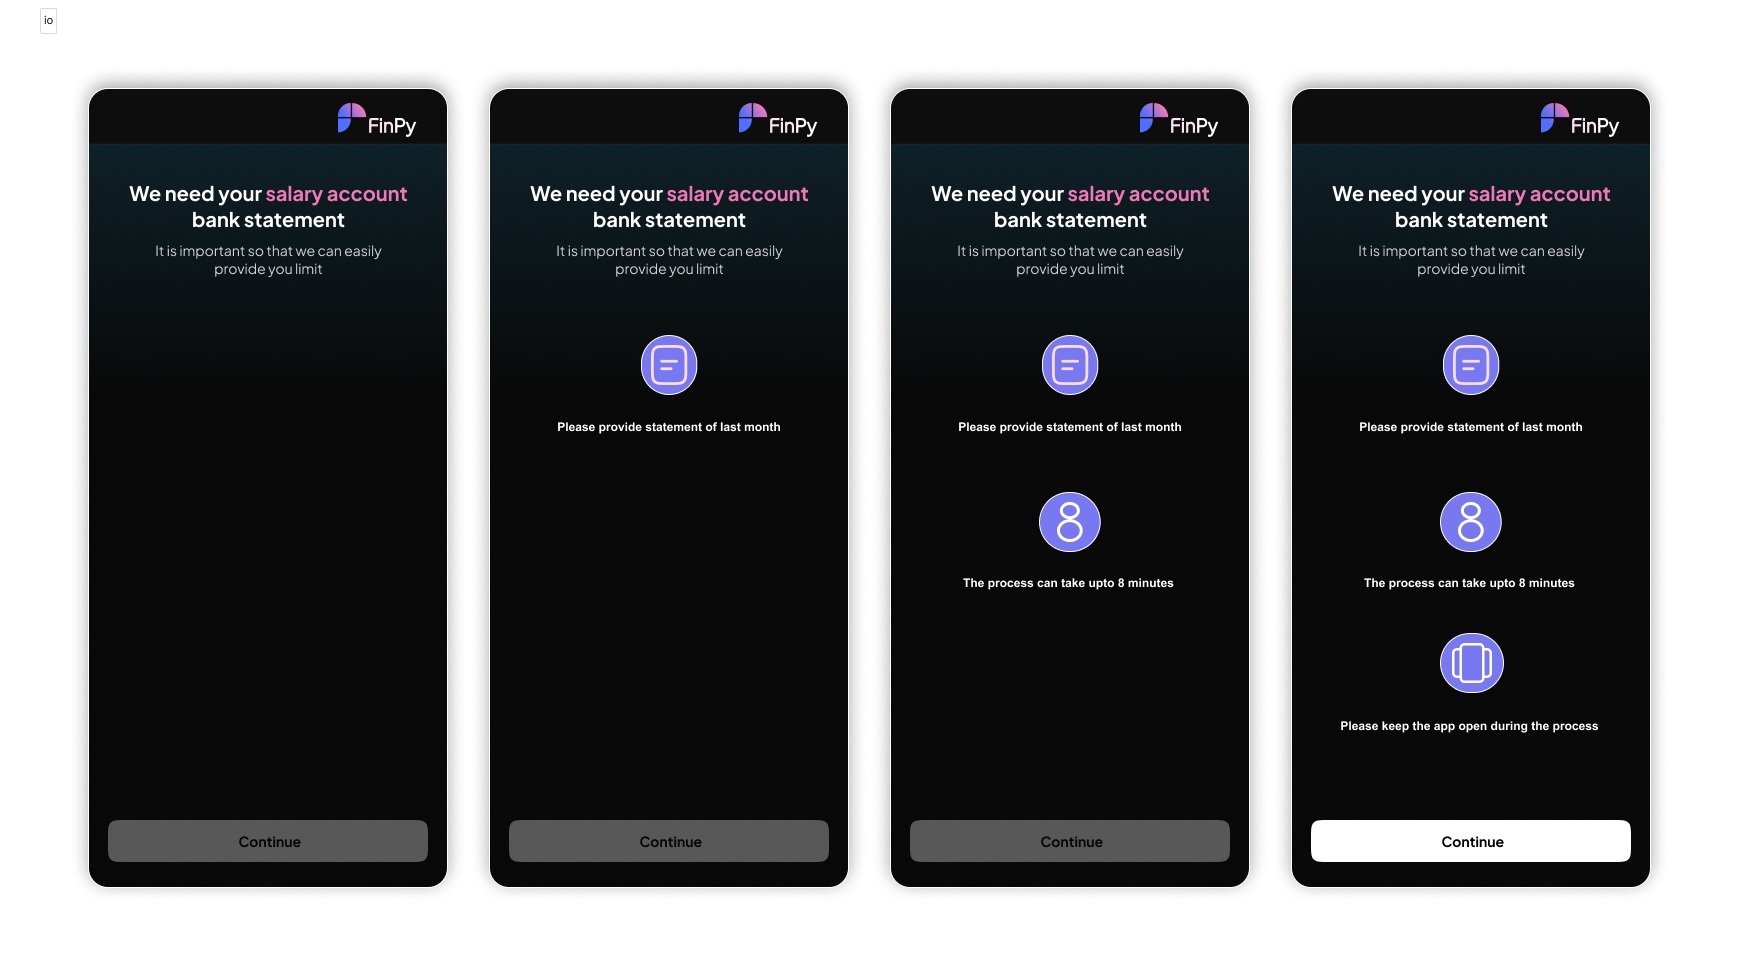
When customers provided account details, it was not a salary account. We initially assumed privacy concerns. Direct user conversations revealed the real problem: users were simply not noticing that salary account details were specifically required. The solution was 'Positive Friction' — a dedicated screen with step-by-step animation, and a CTA that stays inactive for a brief duration to ensure the user reads the information before proceeding.
Problem 3: Promoting Good Repayment Behavior
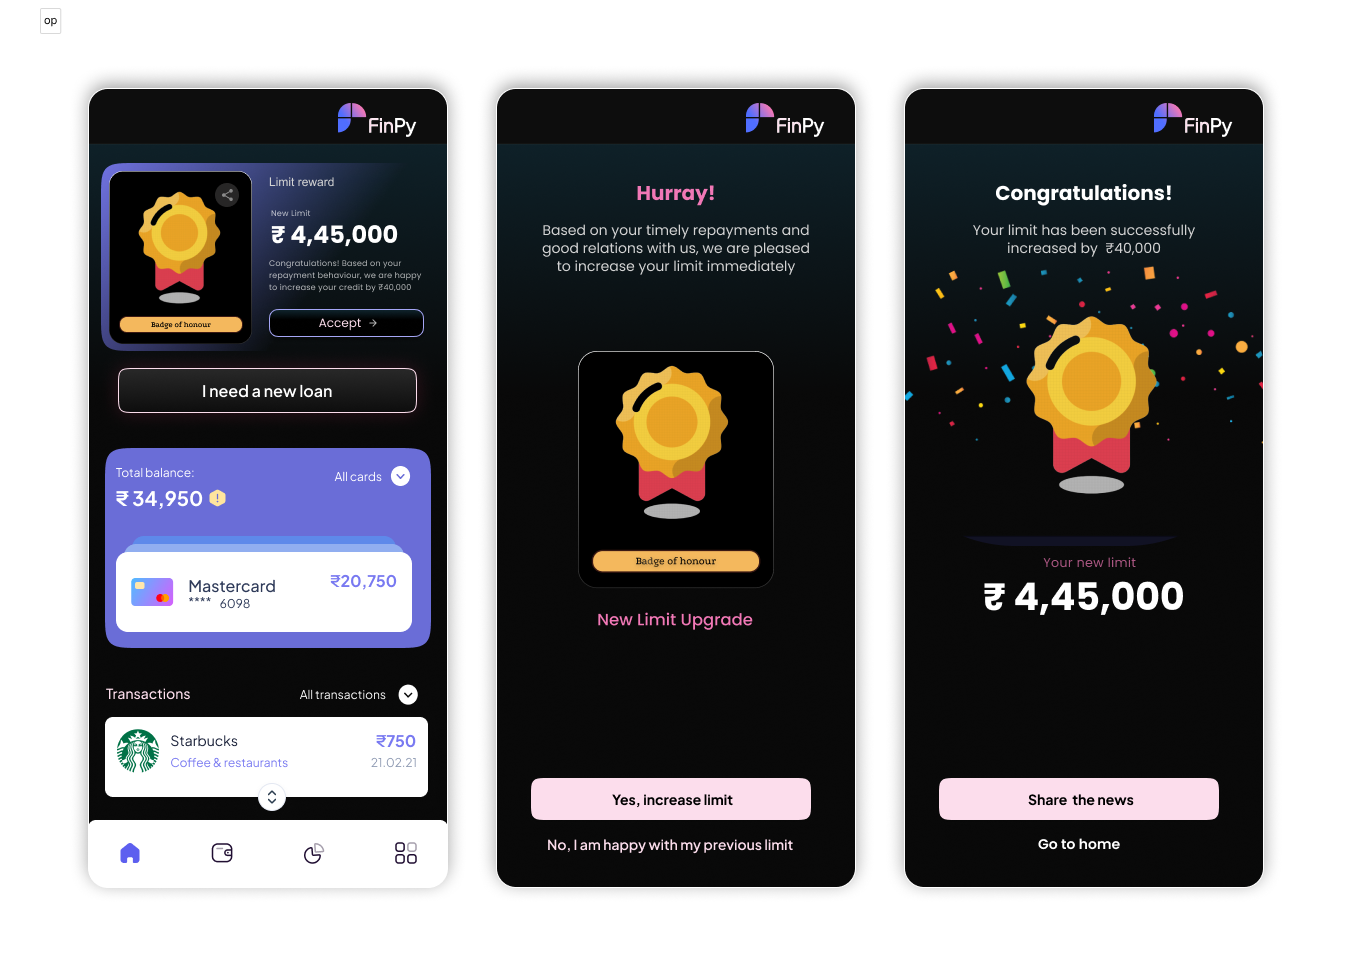
On-time repayment triggered no emotional response — no sense of achievement, no word-of-mouth. The solution: an animated badge system with a 'superhero feeling' that rewards loyalty with an increased credit line. No raw financial data shared, just a compelling feeling of progress. Result: 276 of 320 users accepted the limit increase, 167 clicked 'Share the news', and the feature drove 16 new 5-star Google Play ratings.